
The government has given the green light to the establishment of the Bharat Maritime Insurance Pool, a novel domestic shipping insurance framework supported by a sovereign guarantee of nearly Rs 13,000 crore. This decision comes in the midst of escalating tensions along major global trade routes, leading to a significant surge in insurance costs due to heightened conflict risks.
While marine insurance may seem like a complex topic with little relevance to the average person, the repercussions of increased shipping expenses can subtly impact fuel prices, imported goods, raw materials, and daily household expenditures. Given that over 70% of India’s trade volume and nearly 95% by value rely on maritime routes, the country’s heavy dependence on sea transportation makes it imperative to address such risks.
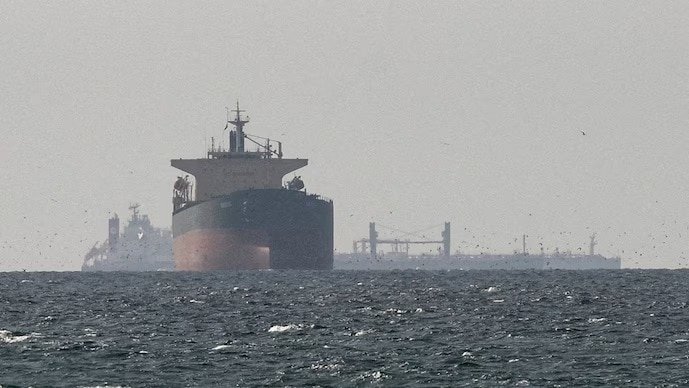
Recent reports have highlighted how tensions in West Asia have already caused a spike in marine insurance premiums, particularly for vessels navigating through the Strait of Hormuz. Consequently, the government’s timely action is a response to these evolving challenges.
The Bharat Maritime Insurance Pool serves as a crucial safety net for Indian shipping, aiming to reduce reliance on foreign insurers during global disruptions. Indian insurers will collaborate to provide coverage for key maritime risks such as ship damage, cargo losses, liabilities including pollution and crew injuries, and war-risk protection for vessels in conflict-prone waters.
This initiative aims to safeguard Indian-flagged and Indian-controlled vessels, as well as those transporting cargo associated with India, in scenarios where overseas insurers may become excessively costly or risk-averse during crises.
By establishing this domestic insurance mechanism, India seeks to mitigate the vulnerabilities stemming from foreign insurance markets, which can lead to sudden premium spikes and limited coverage during times of conflict or instability, ultimately driving up trade costs. Shipping Minister Sarbananda Sonowal emphasized the strategic importance of this move in enhancing India’s maritime trade resilience under challenging global conditions.
Managed by GIC Re and with an initial capacity of around USD 100 million, the pool is backed by a sovereign guarantee from the Indian government, positioning it as a last-resort insurer when global reinsurance or retrocession options are constrained. This not only enhances insurance coverage but also signifies strategic control over critical trade infrastructure, aligning India with countries like the UK, Japan, and South Korea in safeguarding maritime trade interests.
The Bharat Maritime Insurance Pool is expected to offer shipping companies greater certainty during turbulent periods, reduce disruptions for exporters and importers, and provide logistics firms with improved cost visibility. Over time, consumers may benefit from more stable freight and insurance costs, alleviating pressures on imported goods and supply chains.
This initiative underscores the evolving economic policy landscape, where what was once considered a niche financial product now plays a key role in energy security, trade competitiveness, and inflation management. Balasundaram R emphasized that the broader objectives of this move signal India’s strategic intent to enhance self-reliance, fortify resilience against global sanctions, and assert greater sovereign control over critical maritime risks.