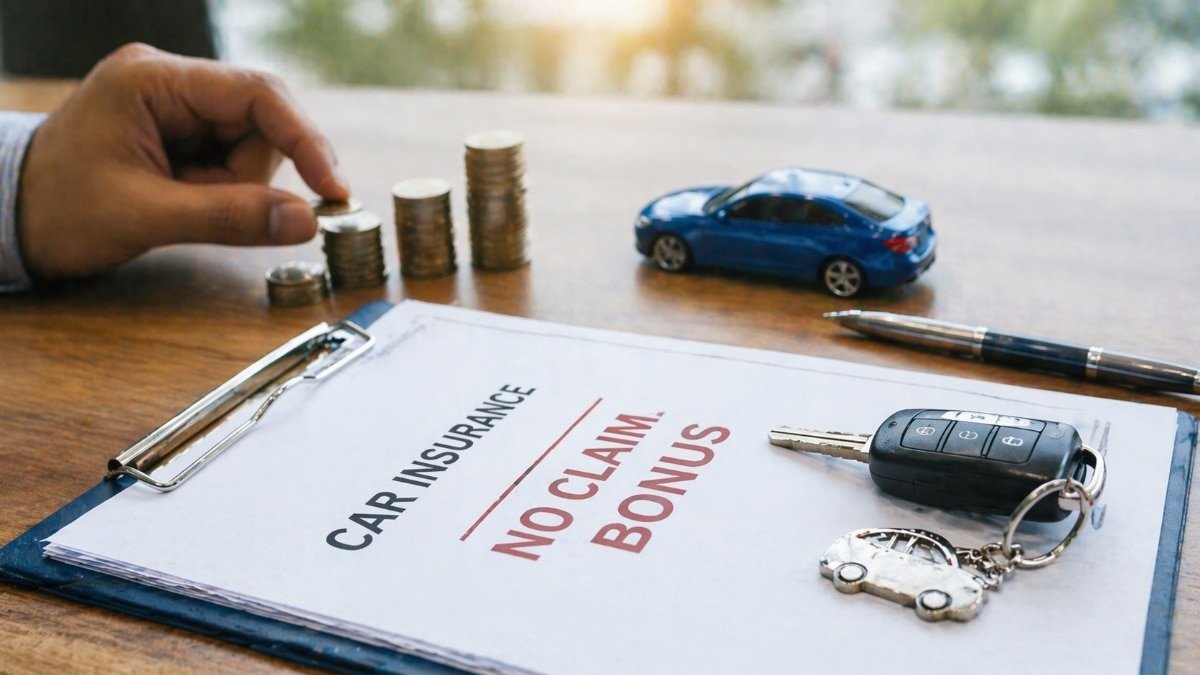

The No Claim Bonus (NCB) is a valuable financial benefit that offers a significant discount on your auto insurance premium for each year you go without making a claim. These discounts typically range from 20% to 50%, increasing gradually with each consecutive claim-free year. It is important to note that the NCB is earned at the time of policy renewal.
A key aspect of the NCB is that it is linked to you as the policyholder, rather than the specific vehicle. This portability feature ensures that the accumulated discounts stay with you even if you decide to switch to a new car or change insurance providers.
Smart car owners should carefully consider the long-term implications of filing a claim versus the immediate repair costs. While it may be tempting to use insurance for minor repairs, small claims often result in a net financial loss over time.
For instance, if you have a dent that costs Rs 2,000 to fix, but you currently enjoy a 35% NCB on a policy with a base Own Damage premium of Rs 6,000, making that claim would reset your bonus to zero. By opting for the Rs 2,000 repair payment, you essentially give up Rs 2,100 in immediate discounts plus future progression value. It is generally advisable to file a claim only when the repair bill significantly exceeds the break-even point of your accumulated NCB savings.
To demonstrate the impact of these savings, let’s consider a policy with an initial own-damage premium of Rs 40,000. In the first claim-free year, a 20% discount saves you Rs 8,000, reducing the premium to Rs 32,000. This discount continues in subsequent years, reaching a 50% cap in the fifth year, lowering the premium to Rs 20,000.
It is important to remember that these figures represent the base premium, and the final amount due will include any additional chosen features and the compulsory third-party insurance component.
The NCB is a discount on the own damage portion of your policy that directly lowers your protection costs. However, certain incidents trigger a reset regardless of fault. For example, if your car is stolen and you claim the full IDV (Insured Declared Value), your NCB will be reset to zero.
Since the bonus is tied to you, it can be transferred by informing your insurer when selling a vehicle and obtaining an NCB protection certificate. It is crucial to renew your policy within a maximum 90-day grace period after expiration to avoid losing your accumulated NCB permanently.
For drivers seeking additional security, many insurers provide an NCB Protect add-on. This feature safeguards your accumulated NCB for at least one claim per year without wiping out the entire bonus. The terms and claim limits vary among providers, with some offering options where a claim may only move you down one level or let you maintain the same level despite a claim. This ensures that one unfortunate incident does not erase years of safe, claim-free driving.
In conclusion, the No Claim Bonus reflects your track record as a responsible driver and is a highly effective way to manage your long-term vehicle ownership expenses. By viewing it as a strategic asset rather than just a simple discount, you can safeguard your savings and ensure that your insurance coverage remains both cost-effective and comprehensive.
Whether through prudent claim handling or the added protection of an NCB Protect plan, maintaining this bonus guarantees that your dedication to road safety continues to pay dividends year after year.